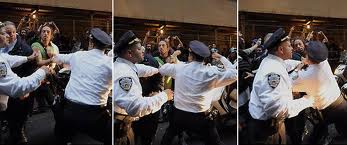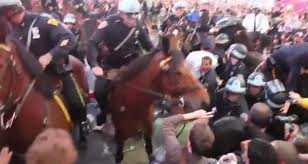Showing posts with label depression. Show all posts

Friday, December 2, 2011

Financial weapons of mass destruction strike again: naked


On October 23, 2008, in the middle of the biggest financial crisis since the Great Depression, Reuters ran an article entitled: “Greenspan says was ‘partially’ wrong on CDS regulation.”

“Former Federal Reserve Chairman Alan Greenspan acknowledged he was "partially" wrong in his belief that some trading instruments, specifically credit default swaps, did not need regulation.
Henry Waxman, the Democrat who chairs the U.S. House of Representatives Committee on Oversight and Government Reform, cited a series of public statements by Greenspan saying the market could handle regulation of derivatives without government intervention.
"My question is simple: Were you wrong?" Waxman said.
Greenspan said he was "partially" wrong in the case of credit default swaps, complex trading instruments meant to act as insurance for bond buyers against default.
"I made a mistake in presuming that the self-interest of organizations, specifically banks and others, was such that they were best capable of protecting their own shareholders and the equity," Greenspan said.
When asked by Waxman if his ideology pushed him to make bad decisions, Greenspan said he found a "flaw" in his governing ideology that has led him to reexamine his thinking” (Dixon 2008).

CDS is an acronym for Credit Default Swap, a credit derivative that resembles insurance in that the buyer pays a premium to the seller in order to protect against the default of another entity. The purchaser of a CDS may have an insurable interest in the entity on which CDS’s are being written, by being a creditor or a bondholder, for example, which consequently means that a legitimate interest in protection against default exists, and the purchase of CDS’s can be seen as constituting a hedge, or a way of managing risk. In case the purchaser does not have an insurable interest, however, the purchase of a CDS is termed “naked” and constitutes nothing more than speculation that the entity on which the CDS is written will default. In case of default or a credit event the seller of the CDS has to pay the CDS holder the previously agreed upon sum, as stipulated in the contract. So while this may seem to be a fairly straight-forward insurance-type product, the fact that these instruments are traded OTC, or “over the counter,” however, means that no one really knows who has written how many CDS’s, on whom, for how much, to whom they have been sold, or whether there is any money to pay out in case of a default. This last point came into focus quite clearly when American International Group (AIG) had to be bailed out by the US taxpayer to the tune of over $180 billion in large part because they did not have any money to pay out on the Credit Default Swaps they had written (Sjostrom Jr. 2008).  

As reported by the BBC, back in 2003, when the notional amount of the entire derivatives market was only $85 trillion, Warren Buffet famously likened them to time bombs and “financial weapons of mass destruction,” some of which seemed to have been devised by “madmen,” and the whole derivatives industry was similar to “hell... easy to enter and almost impossible to exit” (BBC 2003). While Buffet did not specify CDS’s at the time, by September 2011, when, as reported by The Bank of International Settlements (BIS 2011), the entire derivatives market had swollen to over $700 trillion and the notional amount of Credit Default Swaps outstanding was still $32 trillion, down from $62 trillion in 2007, the Financial Times had no problem running an article titled:”CDS: modern day weapons of mass destruction.” The article by Chapman (2011) cited a paper by Calice, Chen and Williams (2011) which found that “for several countries including Greece, Portugal and Ireland the liquidity of the sovereign CDS market has a substantial infuence on sovereign debt spreads,” meaning that CDS’s could contribute to rising bond yields and thus push up borrowing costs and increase the risk of default by sovereign countries. Faced with contagion in the Eurozone and a possible cascade of defaults, the German government, on whose shoulders much of the cost of bailing out the periphery falls, demanded a ban on “naked short selling” and, especially, “naked” CDS’s as well (Baker and Peel 2011).

In an article calling for a ban on “naked” CDS’s Wolfgang Münchau (2010) noted that a “naked CDS...is a purely speculative gamble [without even] one social or economic benefit [which is something that] even hardened speculators agree on. [Moreover a] universally accepted aspect of insurance regulation is that you can only insure what you actually own [and not] even the most libertarian extremist would accept that you could take out insurance on your neighbour’s house or the life of your boss,” especially if you proceeded to light a match to the house or push the boss of a cliff, which, after keeping in mind the findings from above, is what the whole thing amounts to. Greece, Portugal, Ireland, Spain, Italy are all facing ruinous borrowing costs in late 2011 and it is utterly uncertain whether the Eurozone will make it through 2012.

Credit Default Swaps are consequently living up to the moniker given derivatives by Warren Buffett: “financial weapons of mass destruction.” Alan Greenspan, Robert Rubin and Larry Summers refused to consider regulation of CDS’s back in 1997 when Brooksley Born testified before Congress that trading in unregulated derivatives would "threaten our regulated markets or, indeed, our economy without any federal agency knowing about it" (van den Heuvel 2008). They refused, due to the belief noted above that the self-interest of rational economic agents and organizations would be sufficient to prevent the taking on of too much risk and “was such that they were best capable of protecting their own shareholders and the equity.” After admitting that this belief was wrong and that he had found a flaw in his worldview, his ideology, the disciple of Ayn Rand also admitted that: “This modern risk-management paradigm held sway for decades. The whole intellectual edifice, however, collapsed in the summer of last year” (Andrews 2008). We are still dealing with the fallout and should prepare for worse, as reported by zerohedge, who address the meaning and significance of the derivatives market number reported by the BIS being

the biggest ever reported in the financial world: the number in question is $707,568,901,000,000 and represents the latest total amount of all notional Over The Counter (read unregulated) outstanding derivatives...Indicatively, global GDP is about $63 trillion if one can trust any numbers released by modern governments...

for the six month period ended June 30, 2011, the total number of outstanding derivatives surged past the previous all time high of $673 trillion from June 2008, and is now firmly in 7-handle territory: the synthetic credit bubble has now been blown to a new all time high. Another way of looking at the data is that one of the key contributors to global growth and prosperity in the past 10 years was an increase in total derivatives from just under $100 trillion to $708 trillion in exactly one decade. And soon we have to pay the mean reversion price. 

What is probably just as disturbing is that in the first 6 months of 2011, the total outstanding notional of all derivatives rose from $601 trillion at December 31, 2010 to $708 trillion at June 30, 2011. A $107 trillion increase in notional in half a year. 

There is much more than can be said on this topic, and has to be said, because an increase of that magnitude is simply impossible to perceive without alarm bells going off everywhere, especially when one considers the pervasive deleveraging occurring at every sector but the government. All else equal, this move may well explain the massive surge in bank profitability in the first half of the year. It also means that with banks suffering massive losses, and rumors of bank runs and collateral calls, not to mention the aftermath of the MF Global insolvency, the world financial syndicate will have no choice but to increase gross notional even more, even as the market value continues to get ever lower, thus sparking the risk of the mother of all margin calls: a veritable credit fission reaction.
But no matter what: the important thing to remember is that "they are all hedged" - or so they say, a claim we made a completely mockery of a few weeks back. So ex-sarcasm, the now parabolic increase in derivatives means that when the bilateral netting chain is once again broken, and it will be (because AIG was not a one off event), there will simply be trillions more in derivatives that no longer generate a booked cash flow stream for the remaining counterparty, until at the very end, the whole inverted credit0money pyramid collapses in on itself. 

Because once the whole bilateral netting chain is broken, net becomes gross. And gross market value becomes total notional outstanding. And, to quote Hudson, it's game over. 

Expect to see gross market value declines persisting even as the now parabolic increase in total notional persists. At this rate we would not be surprised to see one quadrillion in OTC derivatives by the middle of next year.
And, once again for those confused, the fact that notional had to increase so epically as market value tumbled most likely means that the global derivative pyramid scheme (no pun intended) is almost over.


Saturday, November 19, 2011

To protect and serve the 1% and kick the crap out of everybody else


“If you want a vision of the future, imagine a boot stomping on a human face -- forever.” George Orwell, 1984

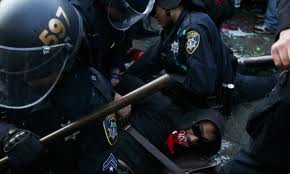
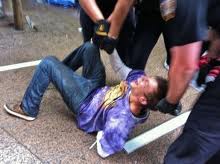
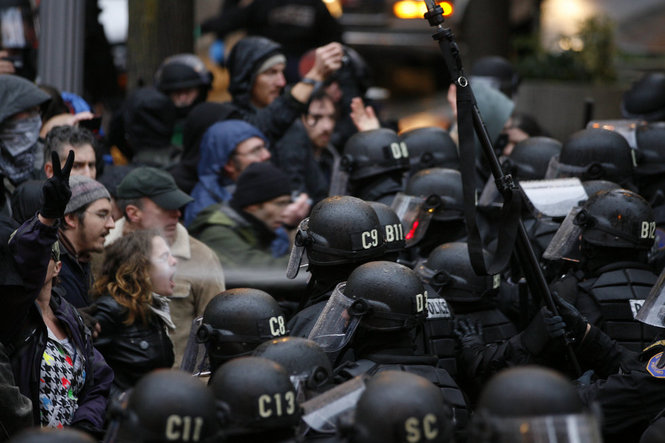
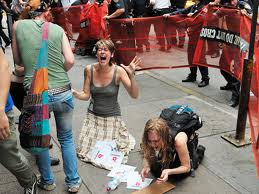
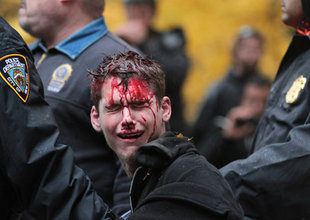
So disillusionment with the powers that be, anger and outrage at bailouts for banks and austerity for everyone else, disappointment with the lack of economic opportunity and excessive debt that can consequently never be paid back, are among the reasons that have led to the formation of the  #OWS (Occupy Wall Street) movement. After two months of peaceful protest and civil disobedience, the protesters have been attacked by the police in a concerted action across the country. Now, the police are obviously here to protect and serve the top one percent of the population that has most of the income and to kick the shit out of anybody else who dares to dissent or protest. Hyperbole, you say? Looking at the following pictures will make even the most law-abiding citizen cringe with disgust, disillusionment and despair. These emotions should quickly give way to outrage, anger and the determination to DO SOMETHING, anything, to fight not only against this level of crass brutality that is not to be accepted or tolerated, but against the corrupt, destructive finance driven junta that seems to have taken over the countries of the West, in what Simon Johnson called the quiet coup.


Friday, March 12, 2010

ECONNED -– The Movie, Um, Video!

Awsome video from Yves Smith!

ECONNED – The Movie, Um, Video!
A very talented movie/commerical/trailer editor, who for some bizarre reason insists on going nameless (but if you want his coordinates, don’t hesitate to ping me) assisted by Ben Fisher in a major role (finding images and video clips) and Richard Smith in a minor role (extensive sanity checking) put this together.

This may inspire McLuhan-esque debates, since I wanted something true to the medium, as in visceral and immediate, rather than the usual talking head sort of piece.

Enjoy! Oh, and turn the sound up


Tuesday, January 26, 2010

Neither Keynes nor Hayek would be happy

Since Obama seems hell bent on doing exactly the wrong thing at the wrong time, namely proposing a spending freeze while jobs are still being lost, as expounded on by Marshall Auerback , here is a little background as to why this is not good by John Carney of the Business Insider:


Wednesday, November 18, 2009

The Precondition for an Economic Recovery According to Keynes and Confirmed by, of all People, Greenspan

Most of the blogosphere has been skeptical of the rally in equities since the beginning, with ZeroHedge pointing out that the rise can be attributed, basically, to free money courtesy of the Federal Reserve, and aided and abetted by High Frequency Trading and the principal program trading of the usual suspects. Now, even for those who are not conspiracy minded, charts such as these speak volumes(pun intended).

From ZeroHedge.


I would like to point out one possible explanation for this phenomenon from a contentious source that I have quoted before. I maintian that Keynes is misunderstoond by many and that he is not the source of all wisdom, but, rather, someone who asked the right questions at the right time and pointed out many problems in the workings of the economy in periods of turmoil.
Unfortunately a serious fall in the marginal efficiency of capital also tends to affect adversely the propensity to consume. For it involves a severe decline in the market value of Stock Exchange equities. Now, on the class who take an active interest in their Stock Exchange investments, especially if they are employing borrowed funds, this naturally exerts a very depressing influence. These people are, perhaps, even more influenced in their readiness to spend by rises and falls in the value of their investments than by the state of their incomes. With a "stock-minded" public as in the United States to-day, a rising stock-market may be an almost essential condition of a satisfactory propensity to consume; and this circumstance, generally overlooked until lately, obviously serves to aggravate still further the depressing effect of a decline in the marginal efficiency of capital.
When once the recovery has been started, the manner in which it feeds on itself and cumulates is obvious. But during the downward phase, when both fixed capital and stocks of materials are for the time being redundant and working-capital is being reduced, the schedule of the marginal efficiency of capital may fall so low that it can scarcely be corrected, so as to secure a satisfactory rate of new investment, by any practicable reduction in the rate of interest. Thus with markets organised and influenced as they are at present, the market estimation of the marginal efficiency of capital may suffer such enormously wide fluctuations that it cannot be sufficiently offset by corresponding fluctuations in the rate of interest. Moreover, the corresponding movements in the stock-market may, as we have seen above, depress the propensity to consume just when it is most needed. In conditions of laissez-faire the avoidance of wide fluctuations in employment may, therefore, prove impossible without a far-reaching change in the psychology of investment markets such as there is no reason to expect. I conclude that the duty of ordering the current volume of investment cannot safely be left in private hands.

The point of contention is, and has been, the last sentence, which raises the blood pressure of everyone involved, on both sides, like nothing else ever written about economics (save maybe Marx). I am not venturing out on a limb when I say that the powers that be have read this passage and drawn their own conclusions from it. Even Greenspan said :
The rise in global stock prices from early March to mid-June is arguably the primary cause of the surprising positive turn in the economic environment. The $12,000bn of newly created corporate equity value has added significantly to the capital buffer that supports the debt issued by financial and non-financial companies. Corporate debt, as a consequence, has been upgraded and yields have fallen. Previously capital-strapped companies have been able to raise considerable debt and equity in recent months. Market fears of bank insolvency, particularly, have been assuaged
.
Juxtaposing these two quotes does not a proof of a government engineered market melt-up make, but one does have to wonder.


Monday, September 21, 2009

Steve Keen on the economy: On the Edge with Max Keiser

Steve Keen is one of the few economists who predicted the financial crisis and he is not at all impressed with the government response arguing that texboox economics failed to predict the crisis and are also not going to solve the problems we are facing. His outlook is less than rosy to say the least.


Saturday, September 19, 2009

Hyman Minsky´s Financial Instability Hypothesis

There is nothing like a crisis of momentous proportions to focus the mind. The intellectual edifice that was neo-classical economics came crumbling down last fall, something admitted by none other than the guru of efficient self-regulating markets himself, Alan Greenspan.


Now a well worn phrase has been that "no one could have seen this coming." Well, that is just not true; many did. And what set them apart from the cheering herd and its Panglossian view that all is for the best in this best of all worlds is that they did not drink from the neo-classical ideological kool-aid.

Hyman Minsky is about the last person asset managers would want to be mentioning in their letters to their clients (I cannot recall where I originally read this, or I would attribute credit). Minsky is perhaps best known for his Financial Instability Hypothesis which is being wonderfully articulated by Steve Keen at his debt deflation blog , along with the good folks over at the Center for Full Employment and Price Stability and many others.

Why the resurgence in interest in Minsky? Well, he explained and expanded ideas set forth by Keynes, who did not believe that markets were efficient and self-regulating. The price of an asset was not always the correct price.

From Keynes´s article in 1937:

Actually, however, we have, as a rule, only the vaguest idea of any but the most direct consequences of our acts. Sometimes we are not much concerned with their remoter consequences, even tho time and chance may make much of them. But sometimes we are intensely concerned with them, more so, occasionally, than with the immediate consequences.

Now of all human activities which are affected by this remoter preoccupation, it happens that one of the most important is economic in character, namely. Wealth. The whole object of the accumulation of Wealth is to produce results, or potential results, at a comparatively distant, and sometimes at an indefinitely distant, date. Thus the fact that our knowledge of the future is fluctuating, vague and uncertain, renders Wealth a peculiarly unsuitable subject for the methods of the classical economic theory. This theory might work very well in a world in which economic goods were necessarily consumed within a short interval of their being produced. But it requires, I suggest, considerable amendment if it is to be applied to a world in which the accumulation of wealth for an indefinitely postponed future is an important factor; and the greater the proportionate part played by such wealth-accumulation the more essential does such amendment become.

By "uncertain" knowledge, let me explain, I do not mean merely to distinguish what is known for certain from what is only probable. The game of roulette is not subject, in this sense, to uncertainty; nor is the prospect of a Victory bond being drawn. Or, again, the expectation of life is only slightly uncertain. Even the weather is only moderately uncertain. The sense in which I am using the term is that in which the prospect of a European war is uncertain, or the price of copper and the rate of interest twenty years hence, or the obsolescence of a new invention, or the position of private wealthowners in the social system in 1970. About these matters there is no scientific basis on which to form any calculable probability whatever. We simply do not know. Nevertheless, the necessity for action and for decision compels us as
practical men to do our best to overlook this awkward fact and to behave exactly as we should if we had behind us a good Benthamite calculation of a series of prospective advantages and disadvantages, each multiplied by its appropriate probability, waiting to he summed.

How do we manage in such circumstances to behave in a manner which saves our faces as rational, economic men? We have devised for the purpose a variety of techniques, of which much the most important are the three following:

(1) We assume that the present is a much more serviceable guide to the future than a candid examination of past experience would show it to have been hitherto. In other words we largely ignore the prospect of future changes about the actual character of which we know nothing.
(2) We assume that the existing state of opinion as expressed in prices and the character of existing output is based on a correct summing up of future prospects, so that we can accept it as such unless and until something new and relevant comes into the picture.
(3) Knowing that our own individual judgment is worthless, we endeavor to fall back on the judgment of the rest of the world which is perhaps better informed. That is, we endeavor to conform with the behavior of the majority or the average. The psychology of a society of individuals each of whom is endeavoring to copy the others leads to what we may strictly term a conventional judgment.

Now a practical theory of the future based on these three principles has certain marked characteristics. In particular, being based on so flimsy a foundation, it is subject to sudden and violent changes. The practice of calmness and immobility, of certainty and security, suddenly breaks down. New fears and hopes will, without warning, take charge of human conduct. The forces of disillusion may suddenly impose a new conventional basis of valuation. All these pretty, polite techniques, made for a well-panelled Board Room and a nicely regulated market, are liable to collapse. At all times the vague panic fears and equally vague and unreasoned hopes are not really lulled, and lie but a little way below the surface.

Perhaps the reader feels that this general, philosophical disquisition on the behavior of mankind is somewhat remote from the economic theory under discussion. But I think not. Tho this is how we behave in the market place, the theory we devise in the study of how we behave in the market place should not itself submit to market-place idols. I accuse the classical economic theory of being itself one of these pretty, polite techniques which tries to deal with the present by abstracting from the fact that we know very little about the
future.

I daresay that a classical economist would readily admit this. But, even so, I think he has overlooked the precise nature of the difference which his abstraction makes between theory and practice, and the character of the fallacies into which he is likely to be led.

Keynes, John Maynard (1937). `The General Theory of Employment`, Quarterly Journal of Economics, 51. cited in Shaw, G.K. (198. The Keynesian Heritage: Volume I. pp.11-13

Minsky identified three types of finance: hedge, speculative and Ponzi. Once the Ponzi stage is reached, debt is taken on in the belief that asset prices will continue to rise which will enable the debt to be serviced. Needless to say, once asset prices start to fall many will default. This is what we are seeing now. From Wray and Tymoigne :

Minsky created a famous taxonomy of financing profiles undertaken by investing firms: hedge (prospective income flows are expected to cover interest and principle with a safe margin); speculative (near-term income flows will cover only interest, although it is expected that finance costs will fall, that income flows will rise, or that assets can be sold at a higher price later—in which case revenues will be sufficient to cover principle); and Ponzi (near-term receipts are insufficient to cover interest payments so that debt increases because the Ponzi unit borrows to cover interest payments). Over the course of an expansion, financial stances evolve from largely hedge to include ever rising proportions of speculative and even Ponzi positions. Some Ponzi positions are undertaken voluntarily (due, for example, to expectations that debt can be refinanced at much more favorable terms or that large capital gains can be realized from asset price appreciation), some are fraudulent (a “pyramid” scheme is an example, in which a crook dupes everlarger numbers of suckers to provide the funds to pay the earliest participants), and some result from disappointment (revenues are lower than expected or finance costs rise unexpectedly). Attempts to raise leverage and to move to more speculative positions can be frustrated at least temporarily: if results turn out to be more favorable than expected, an investor attempting to engage in speculative finance could remain hedge because incomes realized are greater than were anticipated. This is because as aggregate investment rises, it has a multiplier impact on effective demand that can raise sales beyond what had been expected. Later, Minsky explicitly incorporated the Kaleckian result that in the truncated model, aggregate profits equal investment plus the government’s deficit.7 Thus, in an investment boom, profits would be increasing along with investment, helping to validate expectations and encouraging even more investment. This added strength to his proposition that the fundamental instability in the capitalist economy is upward—toward a speculative frenzy (as investment generates profits), which breeds more investment.


Here is an in depth look at the work and ideas of Hyman Mynsky.


Macroeconomics Meets Hyman P. Minsky the Financial Theory of Investment

Friday, September 18, 2009

How much should we fear the "L" shaped economic recovery?

Paul Willmott has an interesting blog post in which he said that he is hoping for one L of a recovery and I have to say I concur wholeheartedly. The economic prognosticators , after peering into their respective crystal balls or tea leaves, have seen the future and declared it a V , U , W, square root and other exotic shapes. Now almost all observers are in agreement that the dreaded L shape which plagued Japan is to be avoided like the pest. Not so Wilmott, the whiz of quantitative finance. He asks:
"Have you any experience of Japan in the 1990s? Well I have. And it didn't seem too bad to me. Were there hordes of people begging on the subway? Not that I recall. Was it dangerous roaming the streets for fear of being mugged? No, it seemed safe enough when I was there. Was there high unemployment and general desititution? No. More on this anon.

Japan in the 1990s was, as it still is, a safe, enjoyable place, with a very high standard of living, and at the cutting edge technology wise. Not the hell hole that economists like to paint. And so I really cannot imagine what Japan would be like now if they'd had a V-shaped recovery. They'd all be communicating by telepathy and travelling via matter transporter I guess.

To me the important point about the economy is not what letter of the alphabet best represents it, nor its percentage growth. After all, is it really necessary to grow at x percent per annum in order to maintain the feeling of status quo? Like the shark, which supposedly has to keep moving forward in order to stay alive. What sort of life is that? I believe what is most important is the well being of the people, and that's not the same as GDP. It is, however, closely linked to rate of employment. And that's where Japan does remarkably well. That's what governments should focus on, to L with growth!"

This flies in the face of the conventional economic wisdom which repeats the words growth and consumption in a manner resembling autism, someting duly noted by the post-autistic economics network .

And for what ultimate purpose do we need this constant economic growth? To continue to live according to Victor Lebow´s encomium of consumption ?
"Our enormously productive economy demands that we make consumption our way of life, that we convert the buying and use of goods into rituals, that we seek our spiritual satisfactions, our ego satisfactions, in consumption. The measure of social status, of social acceptance, of prestige, is now to be found in our consumptive patterns. The very meaning and significance of our lives today expressed in consumptive terms. The greater the pressures upon the individual to conform to safe and accepted social standards, the more does he tend to express his aspirations and his individuality in terms of what he wears, drives, eats- his home, his car, his pattern of food serving, his hobbies.
These commodities and services must be offered to the consumer with a special urgency. We require not only “forced draft” consumption, but “expensive” consumption as well. We need things consumed, burned up, worn out, replaced, and discarded at an ever increasing pace. We need to have people eat, drink, dress, ride, live, with ever more complicated and, therefore, constantly more expensive consumption."

I would prefer instead to turn to Keynes:

"The full employment policy by means of investment is only one particular application of an intellectual theorem. You can produce the result as well by consuming more or working less. Personally I regard the investment policy as first aid… Less work is the ultimate solution.”
Much more on this topic can be found here at econospeak.

Tuesday, September 15, 2009

J.M.Keynes on The Long Term Problem of Full Employment

This has been posted again and again by the good folks at econospeak and I will do my part to try to disseminate the "memo."

THE LONG-TERM PROBLEM OF FULL EMPLOYMENT

J.M. Keynes (May 1943):

1. It seems to be agreed today that the maintenance of a satisfactory level of employment depends on keeping total expenditure (consumption plus investment) at the optimum figure, namely that which generates a volume of incomes corresponding to what is earned by all sections of the community when employment is at the desired level.

2. At any given level and distribution of incomes the social habits and opportunities of the community, influenced (as it may be) by the form and weight of taxation and other deliberate policies and propaganda, lead them to spend a certain proportion of these incomes and to save the balance.

3. The problem of maintaining full employment is, therefore, the problem of ensuring that the scale of investment should be equal to the savings which may be expected to emerge under the above various influences when employment, and therefore incomes, are at the desired level. Let us call this the indicated level of savings.

4. After the war there are likely to ensure [sic] three phases-
(i) when the inducement to invest is likely to lead, if unchecked, to a volume of investment greater than the indicated level of savings in the absence of rationing and other controls;
(ii) when the urgently necessary investment is no longer greater than the indicated level of savings in conditions of freedom, but it still capable of being adjusted to the indicated level by deliberately encouraging or expediting less urgent, but nevertheless useful, investment;
(iii) when investment demand is so far saturated that it cannot be brought up to the indicated level of savings without embarking upon wasteful and unnecessary enterprises.

5. It is impossible to predict with any pretence to accuracy what the indicated level of savings after the war is likely to be in the absence of rationing. We have no experience of a community such as ours in the conditions assumed, with incomes and employment steadily at or near the optimum level over a period and with the distribution of incomes such as it is likely to be after the war. It is, however, safe to say that in the earliest years investment urgently necessary will be in excess of the indicated level of savings. To be a little more precise the former (at the present level of prices) is likely to exceed £m1000 in these years and the indicated level of savings to fall short of this.

6. In the first phase, therefore, equilibrium will have to be brought about by limiting on the one hand the volume of investment by suitable controls, and on the other hand the volume of consumption by rationing and the like. Otherwise a tendency to inflation will set in. It will probably be desirable to allow consumption priority over investment except to the extent that the latter is exceptionally urgent, and, therefore, to ease off rationing and other restrictions on consumption before easing off controls and licences for investment. It will be a ticklish business to maintain the two sets of controls at precisely the right tension and will require a sensitive touch and the method of trial and error operating through small changes.

7. Perhaps this first phase might last five years,-but it is anybody's guess. Sooner or later it should be possible to abandon both types of control entirely (apart from controls on foreign lending). We then enter the second phase, which is the main point of emphasis in the paper of the Economic Section. If two-thirds or three-quarters of total investment is carried out or can be influenced by public or semi-public bodies, a long-term programme of a stable character should be capable of reducing the potential range of fluctuation to much narrower limits than formerly, when a smaller volume of investment was under public control and when even this part tended to follow, rather than correct, fluctuations of investment in the strictly private sector of the economy. Moreover the proportion of investment represented by the balance of trade, which is not easily brought under short-term control, may be smaller than before. The main task should be to prevent large fluctuations by a stable long-term programme. If this is successful it should not be too difficult to offset small fluctuations by expediting or retarding some items in this long-term programme.

8. I do not believe that it is useful to try to predict the scale of this long-term programme. It will depend on the social habits and propensities of a community with a distribution of taxed income significantly different from any of which we have experience, on the nature of the tax system and on the practices and conventions of business. But perhaps one can say that it is unlikely to be less than 7 per cent or more than 20 per cent of the net national income, except under new influences, deliberate or accidental, which are not yet in sight.

9. It is still more difficult to predict the length of the second, than of the first, phase. But one might expect it to last another five or ten years and to pass insensibly into the third phase.

10. As the third phase comes into sight; the problem stressed by Sir H. Henderson begins to be pressing. It becomes necessary to encourage wise consumption and discourage saving,-and to absorb some part of the unwanted surplus by increased leisure, more holidays (which are a wonderfully good way of getting rid of money) and shorter hours.

11. Various means will be open to us with the onset of this golden age. The object will be slowly to change social practices and habits so as to reduce the indicated level of saving. Eventually depreciation funds should be almost sufficient to provide all the gross investment that is required.

12. Emphasis should be placed primarily on measures to maintain a steady level of employment and thus to prevent fluctuations. If a large fluctuation is allowed to occur, it will be difficult to find adequate offsetting measures of sufficiently quick action. This can only be done through flexible methods by means of trial and error on the basis of experience, which has still to be gained. If the authorities know quite clearly what they are trying to do and are given sufficient powers, reasonable success in the performance of the task should not be too difficult.

13. I doubt if much is to be hoped from proposals to offset unforeseen short-period fluctuations in investment by stimulating short-period changes in consumption. But I see very great attractions and practical advantage in Mr Meade's proposal for varying social security contributions according to the state of employment.

14. The second and third phases are still academic. Is it necessary at the present time for Ministers to go beyond the first phase in preparing administrative measures? The main problems of the first phase appear to be covered by various memoranda already in course of preparation. insofar as it is useful to look ahead, I agree with Sir H. Henderson that we should be aiming at a steady long-period trend towards a reduction in the scale of net investment and an increase in the scale of consumption (or, alternatively, of leisure) but the saturation of investment is far from being in sight to-day The immediate task is the establishment and the adjustment of a double system of control and of sensitive, flexible means for gradually relaxing these controls in the light of day-by-day experience

I would conclude by two quotations from Sir H. Henderson's paper, which seem to me to embody much wisdom.

"Opponents of Socialism are on strong ground when they argue that the State would be unlikely in practice to run complicated industries more efficiency than they are run at present. Socialists are on strong ground when they argue that reliance on supply and demand, and the forces of market competition, as the mainspring of our economic system, produces most unsatisfactory results. Might we not conceivably find a modus vivendi for the next decade or so in an arrangement under which the State would fill the vacant post of entrepreneur-in-chief, while not interfering with the ownership or management of particular businesses, or rather only doing so on the merits of the case and not at the behests of dogma?

"We are more likely to succeed in maintaining employment if we do not make this our sole, or even our first, aim. Perhaps employment, like happiness, will come most readily when it is not sought for its own sake. The real problem is to use our productive powers to secure the greatest human welfare. Let us start then with the human welfare, and consider what is most needed to increase it. The needs will change from tune to time, they may shift, for example, from capital goods to consumers' goods and to services. Let us think in terms of organising and directing our productive resources, so as to meet these changing needs, and we shall be less likely to waste them."


There is some serious food for thought here, especially that it "becomes necessary to encourage wise consumption and discourage saving,-and to absorb some part of the unwanted surplus by increased leisure, more holidays (which are a wonderfully good way of getting rid of money) and shorter hours." But this train has left the station. We picked increased consumption to leisure and kept on working ourselves to death in a neverending rat´s race to keep up with the Joneses and driven by manufactured wants. What exactly is it about the 8 hour work day that is sacrosanct? Why does the conventional wisdom insist on equating happiness or welfare with consumption? Is consumption really the be all and end all of human existence? What a poor existence that would be. Unfortunately Keynes was all too soon forgotten and those pesky vested interests he mentioned in the closing pages of his General Theory have to date not stopped trying to discredit his ideas, many of which were misunderstood, never even implemented or seriously considered. Now we are left picking up the pieces of our orgy of consumption, excess and greed that began in the 1980´s. We would do well to read Keynes once more.
The General Theory of Employment, Interest, and Money

Tuesday, July 28, 2009

A Non-Normal Recovery

In my previous post I made the contention that we should not expect a robust recovery and that there was the risk of a "W" shaped double dip. Lets see what the consensus is and whether this is a normal recession as some "green shooters" claim, or something else entirely that no one really wants to acknowledge.


From macroblog, the source of the chart.

The chart plots the four-quarter growth rate of gross domestic product (GDP) from the trough of a recession against the depth of the corresponding contraction, as measured by the cumulative loss of GDP over the course of the downturn. The points within the red circle represent all previous postwar recessions, and they form a nice, neat, easily discernible pattern. That is, the pace of growth in the first year after a recession has, in our history, been reliably related to how bad the recession was. The deeper the recession, the faster the recovery.

The points within the blue circle are based on forecasts of GDP growth from the third quarter of this year through the third quarter of 2010, obtained from the latest issue of Blue Chip Economic Indicators (which reports survey results from "America's leading business economists"). From top left of the circle to bottom right, the points represent the 10 lowest forecasts of the most optimistic members of the 50 Blue Chip forecasting panel, the panel's consensus (or average) forecast, and the 10 highest forecasts of the most pessimistic panel participants.

I chose the third quarter as the reference point because nearly two-thirds of the Blue Chip respondents indicate that, in their view, the recession will indeed end in the third quarter of this year. Assuming this occurs, this recovery would appear to be a big outlier. Either we are about to continue making history—and not in a good way—or current guesses about the medium-term economy are way too pessimistic.

On another note, if you would like to do a little prognosticating of your own, I commend to you our new weekly editions of Economic Highlights and Financial Highlights.

By David Altig, senior vice president and research director at the Atlanta Fed


Well, if the consensus is that the recovery will be absolutely anemic, judging by these low prognostications, then perhaps the "this is a normal recession" meme form the MSM should be dropped because it is incompatible with the consensus forecasts. But we would not want to scare anyone with more truthful reporting, would we? As it turns out, judging by todays consumer confidence index , the US consumer has become cognizant that if one has no job, then there is little reason to rejoice and go on a shopping spree once again in order to jumpstart that 70% of the US economy that depends on consumer spending.


Sunday, July 26, 2009

Outlook for Inflation

As always in such debates there is no consensus to be found as to whether the prices will rise or fall in the foreseeable future in the USA. On the one hand, inflation hawks see a Weimar-esque hyperinflationary financial armageddon brought about by what they consider to be profligate government spending and a complicit central bank providing massive liquidity and engaging in „quantitative easing“ all of which, for inflation hawks, is by definition inflationary. The dramatic increase in the monetary base (see Exhibit 1) has led some commentators to predict rapidly rising inflation and high interest rates (Laffer 2009, SeekingAlpha 2009), firmly following Milton Friedman´s mantra that inflation is always and everywhere a monetary phenomenon (Meltzer 2009). But even such a stalwart conservative economist as Mr Laffer admits in his Wall Street Journal piece that the velocity of circulation is important and that banks will eventually lend enough to become reserve constrained again "given enough time."


David Altig, the vice president of the Atlanta Fed, takes issue with Laffer´s claims and points out that bank lending has actually decreased while the monetary base has increased (see Exhibit 2).


This means that money sitting in banks as excess reserves is not in itself inflationary (Thoma 2009) and since the velocity of circulation has dropped (see Exhibit 3 for an historical view) and there is no evidence that consumers or businesses are becoming more rather than less credit worthy, banks have consequently not increased their lending.


Krugman (2009) draws paralles to the liquidity traps faced by Japan in the 1990´s and the US in the 1930´s (see Exhibit 4).


As pointed out by Hoisington and Hunt (2009) only 1.9% of the increase in reserves was available for lending and bank loans fell an annualized 5.4% from December to March. They add that the velocity of circulation of money can be thought of conceptually as being related to leverage and financial innovation. Needless to say, the world has had its fill of financial innovation for some time and currently deleveraging is a pervasive and prevalent phenomenon. The Fed would like nothing better than to increase the velocity of the circulation of money but since it is unable to, for the reasons outlined below, fears of inflation are misplaced and threaten to prevent a robust recovery and lead to a W shaped double dip or worse.

Those who foresee a deflationary spiral point out that the overleveraged US consumer who has seen a massive drop in the value of assets and is facing rapidly rising unemployment will not be able to spend enough to prop up the economy. There would need to be multiple shifts in the aggregate demand curve and with unemployment rampant wages would seriously lag inflation (Hoisington and Hunt 2009). Moreover, unemployed people tend to spend less money, and people who feel poorer because of the drop in their portfolio, IRA, 401k, and house price are also unlikely to spend enough to cause much inflation. That is, asset price deflation can lead to a debt deflation spiral which interacts with the Keynesian paradox of thrift, along with cost cutting deflation and, as pointed out above, the contraction of bank credit, all of which are individually managable, but together a lethal combination (De Grauwe 2009).


To me, the latter view is much more plausible since inflation is not some bogy out to get us lurking in the shadows, but the succesful passing on of price increases by producers to consumers. On June 16, 2009, amid a slew of terribly economic data, Bloomberg.com reported that wholesale prices dropped 5 percent in the past year and that producer prices ex food and energy dropped 0.1 percent in May. Cost-push factors such as an increase in the price of inputs, for example oil, would not be immidiately passed off to consumers who are purchasing less anyway at lower prices. This all but precludes demand-pull factors triggering inflation, since people have to be willing to pay more for certain goods. In order for this latter to occur, consumers have to be willing and able to spend. The US consumer is overleveraged and has maxed out credit cards, which has led to default rates at credit card companies that are more than the unemployment rate (ZeroHedge 2009).

The precipitous drop in property prices and rise in unemployment
(see Exhibit 5 for unemployment data from Calculated Risk)
are not going to lead to any inflation.


The implied expectations of inflation in long term treasury bond funds reflect constant expectations (see Exhibit 6, Young 2009).


Moreover, even if demand for commodities, especially oil, increases, then there will still need to be a somewhat positive overall sentiment and, actually, dollar weakness, since, when „bearish“ sentiment predominates, then, in a „flight to safety“ investors paradoxically jump into the currency they love to hate, the dollar, whose appreciation will offset the effect of increased demand for commodities on their price. Furthermore, the last oil bubble was undoubtedly fueled by speculation, and, in my humble opinion, so has the current rally in commodities. Aluminum is a prime example of how the price of a commodity can defy supply and demand.

I do not subscribe to the monetarist doctrine that liquidity is per se inflationary. If no one is spending the money, that is, the velocity of circulation is very low, then there will also not be much of a general increase in prices. It should not be forgotten that world demand and consequently economic performance have dropped off a cliff (Eichengreen and O´Rourke 2009) and that because of rising unemployment and the debt and savings dynamics mentioned above we will not return „to happy days again“ anytime soon. What I mean is that the halcyon days of five or ten years ago of rapidly rising asset prices and moderate CPI increases when everyone felt richer and consequently fed huge increases in the value of assets are gone. The US consumer has started to save after decades of living beyond his means but is still faced with a mountain of debt and low or stagnating wages (see Exhibit 6 from sudden debt).


I do not think that much of an economic recovery is going to take place this year and that for the reasons outlined above inflation will not be a problem in the near future.

Of course, I did say „near future.“ To keep inflation in check once a real recovery does set in will take aggressive and, one would hope, enlightened policy responses. Prevention of another massive asset bubble would also help, but this is unlikely. In his book „A Short History of Financial Euphoria“ (1994) John Kenneth Galbraith said that the financial memory lasts about 20 years, until a new generation of wheelers and dealers will fuel the next asset bubble and assure everyone that this time it is different and asset prices can, indeed and contrary to all historical evidence, rise indefinetly.

Tuesday, July 21, 2009

John Kenneth Galbraith´s "The Great Crash"

Having started reading John Kenneth Galbraith´s "The Great Crash: 1929" I cannot help but make a few observations. An old and esteemed professor of mine used to tell us that what was important in critical reading and writing was to answer these three questions: "What does it say? What does it mean? What difference does it make?" Today I can only address the first of these questions, saving the rest for later, hopefully. But back to the first chapter of "The Great Crash."

"[F]or a generation Democrats have been warning that to elect Republicans is to invite another disaster like that of 1929. The defeat of the Democratic candidate in 1952 was widely attributed to the unfortunate appearance at the polls of too many youths who knew only by hearsay of the horrors of those days."

"Historians and novelists always have known that tragedy wonderfully reveals the nature of man. But, while they have made rich use of war, revolution, and poverty, they have been singularly neglectful of financial panics. And one can relish the varied idiocy of human action during a panic to the full, for, while it is a time of great tragedy, nothing is being lost but money."

"On the whole, the greater the earlier reputation for omniscience, the more serene the previous idiocy, the greater the foolishness now exposed. Things that in other times were concealed by a heavy facade of dignity now stood exposed, for the panic suddenly, almost obscenely, snatched this facade away."

"No one was responsible for the great Wall Street crash. No one engineered the speculation that preceded it. Both were the product of the free choice and decisions of hundreds of thousands of individuals. The latter were not led to the slaughter. They were impelled to it by the seminal lunacy which has always seized people who are seized in turn with the notion that they can become very rich."

"It has long been my feeling that the lessons of economics that reside in economic history are important and that history provides an interesting and even fascinating window on economic knowledge."

"Finally, a good knowledge of what happened in 1929 remains our best safeguard against the recurrence of the more unhappy events of those days. Since 1929 we have enacted numerous laws designed to make securities speculation more honest and, it is hoped, more readily restrained."

"The signal feature of the mass escape from reality that occurred in 1929 and before - and which has characterized every previous speculative outburst from the South Sea Bubble to the Florida land boom - was that it carried Authority with it. Governments were either bemused as were the speculators or they deemed it unwise to be sane at a time when sanity exposed one to ridicule, condemnation for spoiling the game, or the threat of severe political retribution."

The relevance and parallels to the current crisis should be obvious.

Wikinvest Wire

ShareThis