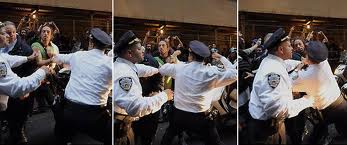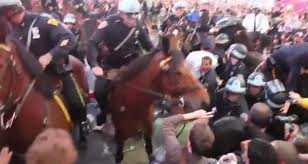“If you want a vision of the future, imagine a boot stomping on a human face -- forever.” George Orwell, 1984
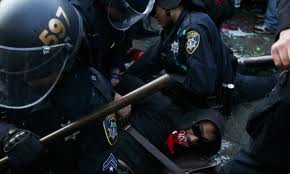
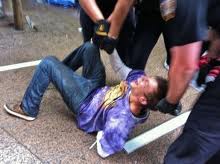
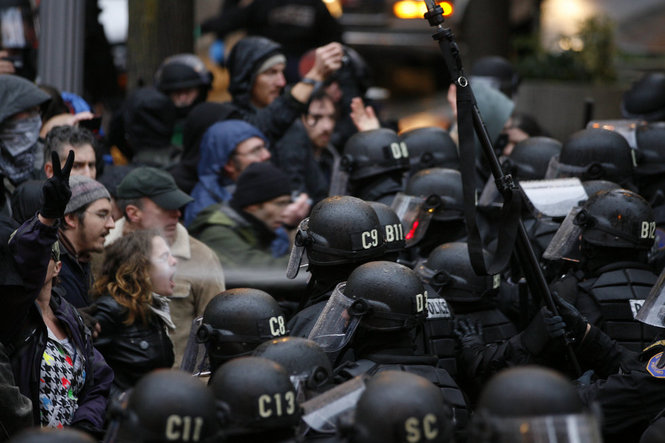
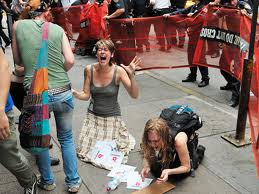
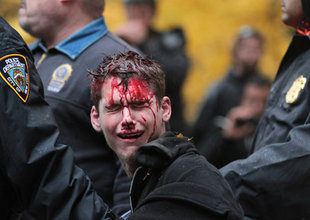
So disillusionment with the powers that be, anger and outrage at bailouts for banks and austerity for everyone else, disappointment with the lack of economic opportunity and excessive debt that can consequently never be paid back, are among the reasons that have led to the formation of the #OWS (Occupy Wall Street) movement. After two months of peaceful protest and civil disobedience, the protesters have been attacked by the police in a concerted action across the country. Now, the police are obviously here to protect and serve the top one percent of the populationthat has most of the income and to kick the shit out of anybody else who dares to dissent or protest. Hyperbole, you say? Looking at the following pictures will make even the most law-abiding citizen cringe with disgust, disillusionment and despair. These emotions should quickly give way to outrage, anger and the determination to DO SOMETHING, anything, to fight not only against this level of crass brutality that is not to be accepted or tolerated, but against the corrupt, destructive finance driven junta that seems to have taken over the countries of the West, in what Simon Johnson called the quiet coup.
Everyone likes to think that they are smarter than the average person. After all, how many of us would be ready to admit that they were in some way, shape or form inferior. Even those friends of ours from high school, and most of us who did not attend private boarding schools know these people, who accorded themselves “street smarts” while telling others that they were merely “book smart,” claim to be better at some things than the average. We all want to feel that we are good at something and even if this is not necessarily the case, we hold on to the illusion that we are somehow more skilled than the average Joe or Jane. Let us call this concept overconfidence.
In the academic literature it is called the overconfidence bias. Cognitive and behavioral psychology as well as behavioral finance and behavioral economics study the concept at length and in depth. Classic examples include asking everyone in a class to rate their driving ability as average, below average or above average. In study after study between 80 and 90 percent of respondents rate their driving ability as above average, which cannot be the case, since only slightly less than half can be above average. Other studies have repeatedly shown that when asked to rate our confidence interval in our statements, we are much more likely to state a much higher confidence level than our accuracy. Most of us like to think that we are smarter than the average, and do not wish to accept that, truthfully, we are probably by definition just about average in many of those attributes that are indeed normally distributed. Some of us might be better at some things than others, obviously, but we are not as superior as we would like to think. Nonetheless, this feeling of being superior, this confidence in our abilities, this sense that we will do better than most everyone else can lead us to take risks we normally would eschew, were it not for the nagging near-certainty that we are better, smarter and more insightful than the others, and that this time, for us, contrary to all evidence and history, things truly will be different, be it in business, investment, games or any other of the myriad activities we engage in where we are in it to win it. Think of housing and stock market bubbles, when real estate speculators and traders or money managers no doubt thought that they would be able to time the market and get rich quickly because of their superior skills and knowledge.
Standardized testing reinforces this bias by inflating the egos of those whose scores are in the upper percentiles. These are the people who get accepted to the best universities, who go on to graduate school because they had GMAT or GRE tutoring classes, and some of these people think that they are the true producers and “value creators” of society, deserving six or seven or eight figure remuneration because of their superior natural or god-given abilities. Everyone else who is not as successful is either morally deficient or intellectually limited and their plight or poverty is therefore deserved and just.
The fundamental attribution error states that the successes of one’s group, class, clan, or tribe, generally called the in-group, are due to internal factors, such as talents, morality, hard work and intelligence, while failures are due to external, uncontrollable causes; with the mirror image being perceived as the reasons for the failures of the out-group, the others: inferior intelligence, lack of talents, or simply laziness, and with the out-group’s successes being consequently simply a matter of luck and often undeserved. So the fundamental attribution error is to attribute success to internal and failure to external factors for oneself or one’s in-group, and the opposite for those in the out-group.
Nowhere is this phenomena more prevalent and on display than in the United States of America, where the current culture war is further being waged on behalf of the top 1%, or was it 0.1%, or 0.01%, who not only receive most of the income but also own most of the wealth in the country. The current battle about “unsustainable” government spending, government needing to live within its means, and ever-present deficit reduction hysteria, is nothing more than an ideological battle being waged by those with means who believe that they should not have to pay any money for those without means, whom they consider shiftless bums and welfare queens who refuse to work and expect “handouts” from the government. Whatever the percentage of poor who do abuse the system, however large, small or inconsequential it might actually be, this discussion is not about them, it is only being framed in this manner. Framing effectsarise when different responses are elicited based on whether the information is presented in a positive or a negative frame. Is the man or woman in dire straits because they were laid off due to downsizing, outsourcing, or company or business failure; or is the person unemployed because they are lazy and want free money from the government. By framing the narrative to portray the less well-off, the unemployed, and the poor in general in the latter manner, stereotypes are being created and reinforced. This is a further cognitive bias at work, the representativeness heuristic, which asks to what extent does A represent B, so to what extend do the poor and unemployed represent my stereotypical image of them. The representativeness bias is thought to be an innate and omnipresent trait, presumably brought about as a function of evolution. The manner in which it is being abused, though, is that through propaganda -- there is no other way to put it -- the unemployed are portrayed as lazy, shiftless, and not wanting to work, but expecting handouts and being able to sit at home drinking or drugging on the taxpayer’s dime. If you work and pay taxes, you are being led to believe that your money is not being spent on military armaments so that the US military can continue blowing up brown people somewhere to make the area safe for liberal capitalism and Halliburton and Bechtel; or that your money is going to bail-out Wall Street; rather, the public is told that taxpayers’ money is going to pay for the immoral and lazy who do not want to work. It is forgotten that the financial system brought about a collapse of the economy bringing along the unemployment that comes with recession and depression. But by reiterating this narrative that the poor and unproductive are unjustly taking money from the rich and productive, powerful interests serving right wing wealth -- see Rupert Murdoch and Roger Ailes along with the Koch brothers, for example -- are framing the discussion to serve their interests, which are to roll back any and all social programs since the New Deal and the Great Society, to take us back to a time when capital was king and the government did not dare tax the hard earned millions or billions of robber barons, when workers knew their place, and corporations would be unhindered in their pursuit of the bottom line, the environment, and the public be damned. Some might say we are already there.
Besides always having been a right wing ideological dream, one could call it Milton Friedman’s “wet dream”, to demolish the social welfare state, to “drown it in a bathtub” as per Grover Norquist`s wishes, currently the unemployed, unions public or private, those on welfare, and all those whose lifetime of work and paying into a system of social security in the expectation of receiving benefits when they retire have seen any government program suddenly become “unsustainable entitlements.” In unison the scream is: “We must cut all social programs or we will go bankrupt,” some louder than others, but all of them singing the same song: the Tea Party, the Republicans, some Democrats, and the President himself, at first unbelievably and unfortunately, but currently obviously and to be expected now that it has become perfectly clear that Obama stands to the right of most civilized conservatives on many issues.
The most insidious lie, however, is not only that the US is going broke because of social welfare programs, but that the US government can go bankrupt at all, after the surreal demonstration of money creation to hand over to an insolvent financial system and their investors and creditors. If one looks at the fact that a sovereign government which is in charge of its own currency can never go bankrupt, something that has long been explained and propounded by Professor L. Randall Wray, Marshall Auerback, Professor Bill Mitchell, Warren Mosler, and many others who understand modern monetary theory; and stunningly admitted by none other than “Helicopter Ben” Bernanke himself, who did indeed drop staggering amounts of money into the laps of the financial sector; and if one finds out from the report of the Special Inspector General of the Troubled Asset Relief Program (SIGTARP report here) presented to Congress by Neil Barofsky, who was in charge of SIGTARP, that up to $23.7 TRILLION were created in guarantees, equity injections, and toxic asset purchases, along with an extensive alphabet soup of programs ostensibly created to bring the US economy back from the brink of Depression and financial Armageddon, then any talk of budget constraint and the US running out of money is ridiculous and disingenuous.
The TARP; regulatory forbearance, which simply means that we will forget a while about bankruptcy rules which state that when you go bankrupt you are out of business, management gets fired and your assets get liquidated to pay your creditors; along with changes in mark-to-market accounting rules which allowed many to get obscenely rich during the bubble years but are now allowing insolvent institutions to hold worthless assets on their balance sheet at inflated prices, further kicking the can down the road in an exercise of extend and pretend; and letting the banking system finance itself at interest rates at 0.25%, money which is then promptly lent back to the government at several percentage points higher, might just strike informed observers as being simply gifts not only to the executives of too-big-to-fail banks for doing such a fantastic job of running their companies into the ground and helping the US economy come to the verge of Depression, but also a bailout of these companies’ bondholders and shareholders, since risk in finance was just a joke, and does not really exist due to the “Bernanke and Uncle Sam put”. “Profits are privatized and losses are socialized,” and everyone should read Yves Smith for her unmatched analysis of the events of the past years.
Once one realizes that for the US government money can simply be created and does not need to be borrowed, and that of the trillions that were created much was simply given away to the US banking and finance sectors and their bondholders, shareholders and creditors, which incidentally also bailed out a lot of foreign banks, then one might realize two things: that free market capitalism no longer exists, if it ever did anyway, when the government selectively chooses whom to rescue and how much money to give away, and that it is not the unemployed, sick and poor who have brought the country to the brink of ruin, but rather an extractive and predatory financial system that has co-opted the government to cater to its needs and not to those of the people. There is a reason it is called “Government Sachs”.
Because people are easily manipulated and susceptible to cognitive and behavioral biases, and because they have a short attention span and are more concerned with celebrity gossip than their own lives, not realizing that they are giving away their life energy to illusions created to keep them docile and distracted, highway robberies and sleight-of-hand such as TARP et. al. can brazenly be pulled and the biggest robbery in history does not concern citizens whose governments now have any protesters beaten bloody by riot police with batons and teargas. It is “bread and circuses” as it has been for most of human history. But when either the “bread” or the “circus” are missing, then people are forced to think about their own existence and maybe, just maybe, see through the corporatist fascist propaganda and wake up enough to become informed, indignant, independent and irrepressible.
Paul Willmott has an interesting blog post in which he said that he is hoping for one L of a recovery and I have to say I concur wholeheartedly. The economic prognosticators , after peering into their respective crystal balls or tea leaves, have seen the future and declared it a V , U , W, square root and other exotic shapes. Now almost all observers are in agreement that the dreaded L shape which plagued Japan is to be avoided like the pest. Not so Wilmott, the whiz of quantitative finance. He asks:
"Have you any experience of Japan in the 1990s? Well I have. And it didn't seem too bad to me. Were there hordes of people begging on the subway? Not that I recall. Was it dangerous roaming the streets for fear of being mugged? No, it seemed safe enough when I was there. Was there high unemployment and general desititution? No. More on this anon.
Japan in the 1990s was, as it still is, a safe, enjoyable place, with a very high standard of living, and at the cutting edge technology wise. Not the hell hole that economists like to paint. And so I really cannot imagine what Japan would be like now if they'd had a V-shaped recovery. They'd all be communicating by telepathy and travelling via matter transporter I guess.
To me the important point about the economy is not what letter of the alphabet best represents it, nor its percentage growth. After all, is it really necessary to grow at x percent per annum in order to maintain the feeling of status quo? Like the shark, which supposedly has to keep moving forward in order to stay alive. What sort of life is that? I believe what is most important is the well being of the people, and that's not the same as GDP. It is, however, closely linked to rate of employment. And that's where Japan does remarkably well. That's what governments should focus on, to L with growth!"
This flies in the face of the conventional economic wisdom which repeats the words growth and consumption in a manner resembling autism, someting duly noted by the post-autistic economics network .
"Our enormously productive economy demands that we make consumption our way of life, that we convert the buying and use of goods into rituals, that we seek our spiritual satisfactions, our ego satisfactions, in consumption. The measure of social status, of social acceptance, of prestige, is now to be found in our consumptive patterns. The very meaning and significance of our lives today expressed in consumptive terms. The greater the pressures upon the individual to conform to safe and accepted social standards, the more does he tend to express his aspirations and his individuality in terms of what he wears, drives, eats- his home, his car, his pattern of food serving, his hobbies.
These commodities and services must be offered to the consumer with a special urgency. We require not only “forced draft” consumption, but “expensive” consumption as well. We need things consumed, burned up, worn out, replaced, and discarded at an ever increasing pace. We need to have people eat, drink, dress, ride, live, with ever more complicated and, therefore, constantly more expensive consumption."
I would prefer instead to turn to Keynes:
"The full employment policy by means of investment is only one particular application of an intellectual theorem. You can produce the result as well by consuming more or working less. Personally I regard the investment policy as first aid… Less work is the ultimate solution.”
Much more on this topic can be found here at econospeak.
This has been posted again and again by the good folks at econospeak and I will do my part to try to disseminate the "memo."
THE LONG-TERM PROBLEM OF FULL EMPLOYMENT
J.M. Keynes (May 1943):
1. It seems to be agreed today that the maintenance of a satisfactory level of employment depends on keeping total expenditure (consumption plus investment) at the optimum figure, namely that which generates a volume of incomes corresponding to what is earned by all sections of the community when employment is at the desired level.
2. At any given level and distribution of incomes the social habits and opportunities of the community, influenced (as it may be) by the form and weight of taxation and other deliberate policies and propaganda, lead them to spend a certain proportion of these incomes and to save the balance.
3. The problem of maintaining full employment is, therefore, the problem of ensuring that the scale of investment should be equal to the savings which may be expected to emerge under the above various influences when employment, and therefore incomes, are at the desired level. Let us call this the indicated level of savings.
4. After the war there are likely to ensure [sic] three phases-
(i) when the inducement to invest is likely to lead, if unchecked, to a volume of investment greater than the indicated level of savings in the absence of rationing and other controls;
(ii) when the urgently necessary investment is no longer greater than the indicated level of savings in conditions of freedom, but it still capable of being adjusted to the indicated level by deliberately encouraging or expediting less urgent, but nevertheless useful, investment;
(iii) when investment demand is so far saturated that it cannot be brought up to the indicated level of savings without embarking upon wasteful and unnecessary enterprises.
5. It is impossible to predict with any pretence to accuracy what the indicated level of savings after the war is likely to be in the absence of rationing. We have no experience of a community such as ours in the conditions assumed, with incomes and employment steadily at or near the optimum level over a period and with the distribution of incomes such as it is likely to be after the war. It is, however, safe to say that in the earliest years investment urgently necessary will be in excess of the indicated level of savings. To be a little more precise the former (at the present level of prices) is likely to exceed £m1000 in these years and the indicated level of savings to fall short of this.
6. In the first phase, therefore, equilibrium will have to be brought about by limiting on the one hand the volume of investment by suitable controls, and on the other hand the volume of consumption by rationing and the like. Otherwise a tendency to inflation will set in. It will probably be desirable to allow consumption priority over investment except to the extent that the latter is exceptionally urgent, and, therefore, to ease off rationing and other restrictions on consumption before easing off controls and licences for investment. It will be a ticklish business to maintain the two sets of controls at precisely the right tension and will require a sensitive touch and the method of trial and error operating through small changes.
7. Perhaps this first phase might last five years,-but it is anybody's guess. Sooner or later it should be possible to abandon both types of control entirely (apart from controls on foreign lending). We then enter the second phase, which is the main point of emphasis in the paper of the Economic Section. If two-thirds or three-quarters of total investment is carried out or can be influenced by public or semi-public bodies, a long-term programme of a stable character should be capable of reducing the potential range of fluctuation to much narrower limits than formerly, when a smaller volume of investment was under public control and when even this part tended to follow, rather than correct, fluctuations of investment in the strictly private sector of the economy. Moreover the proportion of investment represented by the balance of trade, which is not easily brought under short-term control, may be smaller than before. The main task should be to prevent large fluctuations by a stable long-term programme. If this is successful it should not be too difficult to offset small fluctuations by expediting or retarding some items in this long-term programme.
8. I do not believe that it is useful to try to predict the scale of this long-term programme. It will depend on the social habits and propensities of a community with a distribution of taxed income significantly different from any of which we have experience, on the nature of the tax system and on the practices and conventions of business. But perhaps one can say that it is unlikely to be less than 7 per cent or more than 20 per cent of the net national income, except under new influences, deliberate or accidental, which are not yet in sight.
9. It is still more difficult to predict the length of the second, than of the first, phase. But one might expect it to last another five or ten years and to pass insensibly into the third phase.
10. As the third phase comes into sight; the problem stressed by Sir H. Henderson begins to be pressing. It becomes necessary to encourage wise consumption and discourage saving,-and to absorb some part of the unwanted surplus by increased leisure, more holidays (which are a wonderfully good way of getting rid of money) and shorter hours.
11. Various means will be open to us with the onset of this golden age. The object will be slowly to change social practices and habits so as to reduce the indicated level of saving. Eventually depreciation funds should be almost sufficient to provide all the gross investment that is required.
12. Emphasis should be placed primarily on measures to maintain a steady level of employment and thus to prevent fluctuations. If a large fluctuation is allowed to occur, it will be difficult to find adequate offsetting measures of sufficiently quick action. This can only be done through flexible methods by means of trial and error on the basis of experience, which has still to be gained. If the authorities know quite clearly what they are trying to do and are given sufficient powers, reasonable success in the performance of the task should not be too difficult.
13. I doubt if much is to be hoped from proposals to offset unforeseen short-period fluctuations in investment by stimulating short-period changes in consumption. But I see very great attractions and practical advantage in Mr Meade's proposal for varying social security contributions according to the state of employment.
14. The second and third phases are still academic. Is it necessary at the present time for Ministers to go beyond the first phase in preparing administrative measures? The main problems of the first phase appear to be covered by various memoranda already in course of preparation. insofar as it is useful to look ahead, I agree with Sir H. Henderson that we should be aiming at a steady long-period trend towards a reduction in the scale of net investment and an increase in the scale of consumption (or, alternatively, of leisure) but the saturation of investment is far from being in sight to-day The immediate task is the establishment and the adjustment of a double system of control and of sensitive, flexible means for gradually relaxing these controls in the light of day-by-day experience
I would conclude by two quotations from Sir H. Henderson's paper, which seem to me to embody much wisdom.
"Opponents of Socialism are on strong ground when they argue that the State would be unlikely in practice to run complicated industries more efficiency than they are run at present. Socialists are on strong ground when they argue that reliance on supply and demand, and the forces of market competition, as the mainspring of our economic system, produces most unsatisfactory results. Might we not conceivably find a modus vivendi for the next decade or so in an arrangement under which the State would fill the vacant post of entrepreneur-in-chief, while not interfering with the ownership or management of particular businesses, or rather only doing so on the merits of the case and not at the behests of dogma?
"We are more likely to succeed in maintaining employment if we do not make this our sole, or even our first, aim. Perhaps employment, like happiness, will come most readily when it is not sought for its own sake. The real problem is to use our productive powers to secure the greatest human welfare. Let us start then with the human welfare, and consider what is most needed to increase it. The needs will change from tune to time, they may shift, for example, from capital goods to consumers' goods and to services. Let us think in terms of organising and directing our productive resources, so as to meet these changing needs, and we shall be less likely to waste them."
There is some serious food for thought here, especially that it "becomes necessary to encourage wise consumption and discourage saving,-and to absorb some part of the unwanted surplus by increased leisure, more holidays (which are a wonderfully good way of getting rid of money) and shorter hours." But this train has left the station. We picked increased consumption to leisure and kept on working ourselves to death in a neverending rat´s race to keep up with the Joneses and driven by manufactured wants. What exactly is it about the 8 hour work day that is sacrosanct? Why does the conventional wisdom insist on equating happiness or welfare with consumption? Is consumption really the be all and end all of human existence? What a poor existence that would be. Unfortunately Keynes was all too soon forgotten and those pesky vested interests he mentioned in the closing pages of his General Theory have to date not stopped trying to discredit his ideas, many of which were misunderstood, never even implemented or seriously considered. Now we are left picking up the pieces of our orgy of consumption, excess and greed that began in the 1980´s. We would do well to read Keynes once more. The General Theory of Employment, Interest, and Money
As always in such debates there is no consensus to be found as to whether the prices will rise or fall in the foreseeable future in the USA. On the one hand, inflation hawks see a Weimar-esque hyperinflationary financial armageddon brought about by what they consider to be profligate government spending and a complicit central bank providing massive liquidity and engaging in „quantitative easing“ all of which, for inflation hawks, is by definition inflationary. The dramatic increase in the monetary base (see Exhibit 1) has led some commentators to predict rapidly rising inflation and high interest rates (Laffer 2009, SeekingAlpha 2009), firmly following Milton Friedman´s mantra that inflation is always and everywhere a monetary phenomenon (Meltzer 2009). But even such a stalwart conservative economist as Mr Laffer admits in his Wall Street Journal piece that the velocity of circulation is important and that banks will eventually lend enough to become reserve constrained again "given enough time."
David Altig, the vice president of the Atlanta Fed, takes issue with Laffer´s claims and points out that bank lending has actually decreased while the monetary base has increased (see Exhibit 2).
This means that money sitting in banks as excess reserves is not in itself inflationary (Thoma 2009) and since the velocity of circulation has dropped (see Exhibit 3 for an historical view) and there is no evidence that consumers or businesses are becoming more rather than less credit worthy, banks have consequently not increased their lending.
Krugman (2009) draws paralles to the liquidity traps faced by Japan in the 1990´s and the US in the 1930´s (see Exhibit 4).
As pointed out by Hoisington and Hunt (2009) only 1.9% of the increase in reserves was available for lending and bank loans fell an annualized 5.4% from December to March. They add that the velocity of circulation of money can be thought of conceptually as being related to leverage and financial innovation. Needless to say, the world has had its fill of financial innovation for some time and currently deleveraging is a pervasive and prevalent phenomenon. The Fed would like nothing better than to increase the velocity of the circulation of money but since it is unable to, for the reasons outlined below, fears of inflation are misplaced and threaten to prevent a robust recovery and lead to a W shaped double dip or worse.
Those who foresee a deflationary spiral point out that the overleveraged US consumer who has seen a massive drop in the value of assets and is facing rapidly rising unemployment will not be able to spend enough to prop up the economy. There would need to be multiple shifts in the aggregate demand curve and with unemployment rampant wages would seriously lag inflation (Hoisington and Hunt 2009). Moreover, unemployed people tend to spend less money, and people who feel poorer because of the drop in their portfolio, IRA, 401k, and house price are also unlikely to spend enough to cause much inflation. That is, asset price deflation can lead to a debt deflation spiral which interacts with the Keynesian paradox of thrift, along with cost cutting deflation and, as pointed out above, the contraction of bank credit, all of which are individually managable, but together a lethal combination (De Grauwe 2009).
To me, the latter view is much more plausible since inflation is not some bogy out to get us lurking in the shadows, but the succesful passing on of price increases by producers to consumers. On June 16, 2009, amid a slew of terribly economic data, Bloomberg.com reported that wholesale prices dropped 5 percent in the past year and that producer prices ex food and energy dropped 0.1 percent in May. Cost-push factors such as an increase in the price of inputs, for example oil, would not be immidiately passed off to consumers who are purchasing less anyway at lower prices. This all but precludes demand-pull factors triggering inflation, since people have to be willing to pay more for certain goods. In order for this latter to occur, consumers have to be willing and able to spend. The US consumer is overleveraged and has maxed out credit cards, which has led to default rates at credit card companies that are more than the unemployment rate (ZeroHedge 2009).
The implied expectations of inflation in long term treasury bond funds reflect constant expectations (see Exhibit 6, Young 2009).
Moreover, even if demand for commodities, especially oil, increases, then there will still need to be a somewhat positive overall sentiment and, actually, dollar weakness, since, when „bearish“ sentiment predominates, then, in a „flight to safety“ investors paradoxically jump into the currency they love to hate, the dollar, whose appreciation will offset the effect of increased demand for commodities on their price. Furthermore, the last oil bubble was undoubtedly fueled by speculation, and, in my humble opinion, so has the current rally in commodities. Aluminum is a prime example of how the price of a commodity can defy supply and demand.
I do not subscribe to the monetarist doctrine that liquidity is per se inflationary. If no one is spending the money, that is, the velocity of circulation is very low, then there will also not be much of a general increase in prices. It should not be forgotten that world demand and consequently economic performance have dropped off a cliff (Eichengreen and O´Rourke 2009) and that because of rising unemployment and the debt and savings dynamics mentioned above we will not return „to happy days again“ anytime soon. What I mean is that the halcyon days of five or ten years ago of rapidly rising asset prices and moderate CPI increases when everyone felt richer and consequently fed huge increases in the value of assets are gone. The US consumer has started to save after decades of living beyond his means but is still faced with a mountain of debt and low or stagnating wages (see Exhibit 6 from sudden debt).
I do not think that much of an economic recovery is going to take place this year and that for the reasons outlined above inflation will not be a problem in the near future.
Of course, I did say „near future.“ To keep inflation in check once a real recovery does set in will take aggressive and, one would hope, enlightened policy responses. Prevention of another massive asset bubble would also help, but this is unlikely. In his book „A Short History of Financial Euphoria“ (1994) John Kenneth Galbraith said that the financial memory lasts about 20 years, until a new generation of wheelers and dealers will fuel the next asset bubble and assure everyone that this time it is different and asset prices can, indeed and contrary to all historical evidence, rise indefinetly.